

Inside the $1.3B digital twin market: Why no vendor owns the full stack
SOURCE: IOT-ANALYTICS.COM
SEP 03, 2026

?

In short
- The standalone digital twin market reached $1.3 billion in 2025 and is forecast to grow to $4.2 billion by 2030, while the broader enabling software ecosystem reached $175 billion, according to IoT Analytics’ Digital Twin & Simulation Software Market Report 2026–2030.
- The digital twin tech stack and market span 4 workflow contexts and 5 technology layers, and no vendor owns the full tech stack.
- Most suppliers are strong in only a few layers, making domain expertise, partnerships, interoperability, and integration central to how the market operates.
- Those wanting to adopt digital twins should start by defining the decision or workflow to improve, then select the required capabilities and assess whether dedicated digital twin software is needed.
In this article
- The digital twin market: A $1.3 billion product market sits inside a $175 billion ecosystem
- What is a digital twin?
- How we classify digital twins
- The digital twin market landscape 2026
- Why no vendor owns the whole digital twin stack
- How adopters should think about building digital twins‘
- Further research
- Narrow digital twin vendors’ market share (Insights+ Exclusive)
- General drivers and inhibitors for the digital twin & simulation market (Insights+ Exclusive)
- Highest value areas for digital twins and 4 deep dives (Insights+ Exclusive)
The digital twin market: A $1.3 billion product market sits inside a $175 billion ecosystem

Standalone digital twin software a small market despite strong growth. Spending on standalone digital twin software, where “digital twin” is the precise product being sold on its own, reached $1.3 billion in 2025, according to IoT Analytics’ 230-page Digital Twin & Simulation Software Market Report 2026–2030 (published July 2026). We expect spending to grow at 27% CAGR until 2030, when it reaches $4.2 billion. That is healthy growth, but the numbers pale in comparison to spending on broader software that supplies digital twin capabilities (e.g., CAD, PLM, data visualization, analytics, and simulation software), which reached $175 billion in 2025. Revenue directly monetized as standalone digital twin software thus represents approximately 0.7% of the broader software ecosystem that enables digital twins.
| $175B spent in 2025 on software that supplies digital twin capabilities | $1.3B of that spent on standalone digital twin software | 0.7% the standalone share of all digital twin ecosystem spending |
Why the drastic difference? It is not that no one wants digital twins; $1.3 billion is still a sizeable market. In our 2024 Smart Factory survey (N=500), 48.2% named digital twins a top priority for the next 3–5 years. Further, search interest in digital twins spiked starting in mid-2025, remaining relatively high compared to the muted, stable interest from 2020 to the start of 2025. Even in our regular discussions with vendors and manufacturers, interest in digital twins remains high.
Instead, the gap is structural. “Digital twin” is a compelling, widely applicable concept but a poorly defined purchasing category. Organizations create digital twins using engineering, operational, simulation, visualization, or analytics software, but they can rarely buy a complete digital twin as a single, off-the-shelf product. That is why so many vendors market digital twins, yet few vendors sell one standalone:
Vendors often sell something else, and the twin emerges from the workflow that software supports
Insights from this article are derived from
Digital Twin & Simulation Software Market Report 2026–2030
A 230-page report detailing the market for digital twins and simulation software, including definition & disambiguation, standardization efforts, market size & outlook, competitive landscape, case studies, trends & developments.

Already a subscriber? View your reports and trackers here ?
What is a digital twin?
A digital twin is a virtual model that replicates the behavior of an existing or potential real-world asset, process, system, or group of interconnected systems. This is the definition IoT Analytics uses for its digital twin market research.
Based on that definition, we see 2 boundaries that decide what counts as a digital twin and how the market is sized:
- A digital twin is a model and not the application thereof. A digital twin is, first and foremost, a model of reality and need not include simulation, visualization, or prediction. Those are common applications of a twin but not the twin itself. However, a simulation, prediction, or visualization can be built on a digital twin but does not have to. Vendor messaging frequently conflates the two (model and application).
- Digital Twin software is often part of other software. In practice, the digital twin capability is often a property of an existing tool (e.g., a simulation, prediction, or visualization product) rather than a product in its own right. Standalone digital twin modeling tools do exist; they are just the exception.
Those boundaries are why we size 3 markets in our Digital Twin & Simulation Software Market Report 2026–2030:
- Narrow standalone market – $1.3B
- Adjacent simulation market – $11.8B
- Broad ecosystem of everything that supplies twin capabilities – $175B
How we classify digital twins
Our previous classification model: The 3D classification cube
Digital twin market structure outgrew the original 3D framework. IoT Analytics market research on digital twins dates back to 2020, with the Digital Twin Insights Report 2020. In April that year, we published the article “How the world’s 250 Digital Twins compare? Same, same but different,” built around a 3D classification of digital twins:
- By hierarchical level
- By lifecycle phase
- By use
That framework has been widely adopted since then, and we stand behind it as a way to define what a digital twin is today.
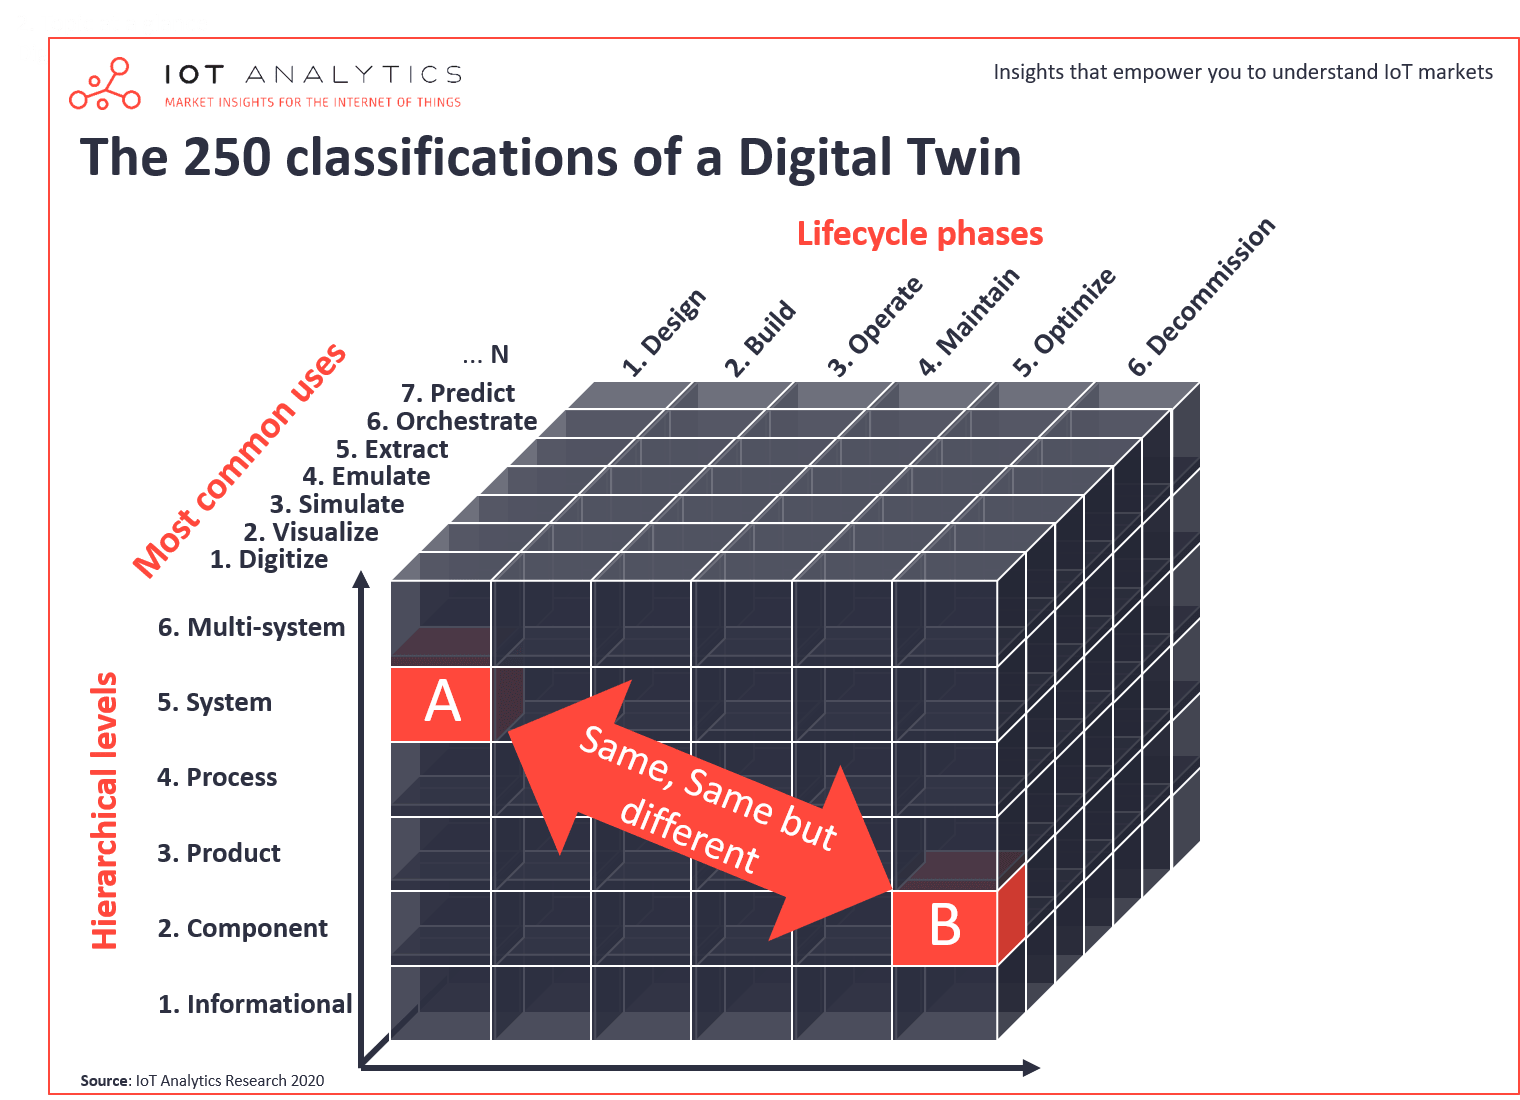
3D classification cube of digital twin technology (source: April 2020 IoT Analytics article on digital twins)
Over the last few years, the 3D cube, or a version of it, has helped many discussions cut through the complexities of digital twin development. One deficiency that our discussions over the last 3 years have shown, though, is that while it aids discussions, it does not necessarily reflect how the market for digital twins is structured. Commercially, the market does not organize itself along hierarchical levels and only partially along lifecycle phases. Our updated view for 2026 is that the market organizes into 1) workflow contexts abd and, within each, into 2) layers of a technology stack.
The new model: 4 workflow contexts and 5 technology layers define the end-to-end digital twin tech stack landscape
Digital twin vendors now cluster by workflow and technology layer. Our 2026 mapping sorts the vendors in the digital twin ecosystem into 5 technology layers, inside 4 workflow contexts.
The 5 layers, from bottom to top:
- Data sources & enterprise systems – CAD, PLM, simulation, SCADA, MES/MOM, historians, data platforms, BIM/BMS, GIS, reality capture, NMS/OSS, EMS/DMS, and CMDB/config. This is where the raw material of a twin lives, owned by the incumbents of each discipline.
- Data connectivity & model integration – Engineering-model integration on 1 side, operational-data integration on the other. This is where most digital twin programs stall, and it is contested by industrial DataOps vendors, IoT platforms, and the enterprise-system vendors themselves.
- Digital twin modeling – The narrow, $1.3 billion (2025) market. This is the only layer where “digital twin” is the product being sold, and it is the thinnest layer in the stack.
- Infrastructure enablers – Compute and horizontal developer platforms, such as those from NVIDIA, AMD, Intel, HPE, Lenovo, and Dell.
- Applications – Visualize, simulate, test and validate, predict and optimize, and control. These are the outcomes buyers actually pay for.
We have preserved the “use” (applications) dimension from the cube, as it survives as the applications layer at the top of the stack.
The 4 workflow contexts:
- Design & engineering – Digital twins of existing and future products, often as an extension of CAD, PLM, or simulation software.
- Industrial operations – Digital twins of entire factories, production lines, or process plants, often as an extension of MES/MOM, industrial automation, or plant-simulation software.
- Buildings & infrastructure – Digital twins of buildings, campuses, data centers, or other built environments, often as an extension of BIM/BMS or GIS software.
- Networks & systems – Digital twins of communications networks, electricity grids, and water networks, often as an extension of domain-specific software such as EMS.
Historically, the workflows have rarely connected. The tool that builds a digital twin of a building has limited overlap with the tool that builds a digital twin of an electricity grid. They share a concept (i.e., you are modeling something real) and almost nothing else: different data sources, different fidelity requirements, different simulation methods, different buyers, different vendors.
The digital twin market landscape 2026
No vendor controls the fragmented digital twin technology stack. Above is the tech stack in practice. As part of the research, IoT Analytics identified over 1,500 vendors that cater to parts (not all) of the digital twin ecosystem, with a small share of major players listed in the above graphic. Across the different stack elements, 10 different types of companies are contributing to the wider digital twin market and ecosystem:
- Cloud hyperscalers (e.g., Microsoft and AWS)
- Industrial automation & controls (e.g., Siemens, ABB, Rockwell Automation, Schneider Electric, and Emerson)
- Simulation & CAE software (e.g., Ansys, MathWorks, and Altair)
- IoT platforms (e.g., Cumulocity and ClearBlade)
- PLM & CAD (e.g., Dassault Systèmes, PTC, and Autodesk)
- AEC & GIS (e.g., Bentley, Autodesk, and Hexagon)
- Reality capture (e.g., NavVis and Matterport)
- Industrial DataOps & UNS (e.g., Litmus and Cognite)
- Compute enablers (e.g., NVIDIA, AMD, and Intel)
- Visualization enablers (e.g., Unity and Cesium)
Each archetype arrives with genuine strength at 1 or 2 layers but has dependencies everywhere else, i.e., no one owns the digital twin tech stack.
Why no vendor owns the whole digital twin tech stack
Structural complexity keeps the digital twin market fragmented. If the concept of a digital twin is widely wanted, why has no vendor built the 1 platform that does it all? We found 4 structural reasons why the stack remains fragmented.
- Digital twins are not a clearly bounded software category. A digital twin is primarily an architectural concept applied across existing engineering, OT, cloud, data, and enterprise software ecosystems. Those ecosystems are deeply embedded in customers’ operations, so no vendor can simply replace them with a new, self-contained digital twin stack.
- The stack combines fundamentally different software disciplines. A twin may need asset connectivity, data management, semantic modeling, engineering simulation, 3D visualization, workflow integration, analytics, and application development. Few vendors are genuinely strong across more than 2 or 3 of those layers.
- Domain expertise matters as much as platform breadth. A twin of a power grid, a semiconductor, a factory, an aircraft engine, or an office building requires different models, data structures, engineering logic, and operational workflows. Horizontal platforms supply the infrastructure; domain-specific vendors supply the models and applications that make the twin useful.
- Consolidation broadens portfolios but does not eliminate fragmentation. Major vendors are acquiring simulation, industrial data, IoT, visualization, and application capabilities, e.g., Synopsys–Ansys (2025), Siemens–Altair (2025), and Cadence–Hexagon D&E (2025). But each deal typically adds only part of the stack, and the acquired products keep separate architectures, data models, and licensing. Portfolio breadth does not automatically become a unified, end-to-end offering.
Siemens is the clearest illustration of #3: it sells a digital twin for the grid, a digital twin for buildings, and a factory digital twin composer (released in early 2026). These are 3 products, 3 workflow contexts, and 1 vendor, yet not a single digital twin product. What Siemens does have is a set of workflow-specific tools that each qualify as a digital twin.
The result looks a lot like the IoT platform market before it: even the broadest players operate through partnerships rather than around them. Ansys integrates with NVIDIA Omniverse and cloud HPC; Bentley combines iTwin with Google geospatial data; AWS leans on partners such as Ansys for simulation-led deployments.
How adopters should think about building digital twins
Adopters should NOT begin by selecting a digital twin platform
Adopters should start with outcomes rather than digital twin platforms. Most organizations want a digital twin. However, in our view, adopters should not begin by selecting a digital twin platform or trying to build a twin of an entire asset or organization. They should first identify the decision, workflow, or business outcome they want to improve. From there, they can determine which capabilities are required across the technology stack and whether dedicated digital twin software should form part of the solution.
Once the target decision and workflow are clear, adopters can identify the required data sources, integration capabilities, models, infrastructure, and applications.
Important:
- In some cases, these capabilities will already exist inside (existing) engineering, simulation, operational, or analytics software.
- In others, a dedicated digital twin product may provide the modeling, integration, or orchestration layer needed to bring them together.
A useful framework: Digital twins create the most value where urgency meets fit
Inside the wider $175 billion ecosystem, digital twins are everywhere, and many believe that, sooner or later, almost everything will have a twin. That makes the useful question not “which twin do I build?” but “what kind of twin actually pays off now?” To answer it, we built a simple framework and classified digital twin scenarios against it.
Digital twin returns depend on urgency and structural fit. Across the 4 workflow contexts, 6 factors determine whether a digital twin generates material returns. The first 2 establish urgency, i.e., the “why act now”:
- High cost of error: mistakes are expensive, unsafe, or slow to reverse. Rolls-Royce predicts engine failures to avoid costly disruption and testing delays.
- High pressure to shorten timelines: BMW compressed production setup from weeks to days under the pressure of launching 40 new vehicles.
The next 4 establish fit, i.e., whether the workflow is structurally suited to a twin at all:
- High simulation leverage: virtual testing displaces physical prototypes and commissioning risk. Wipro PARI cut rework by 40–50% through virtual commissioning of assembly lines.
- High system interdependence: The Shard coordinates structural, spatial, and MEP systems with real-time clash detection.
- High data availability: Thames Water combines smart meters, acoustic loggers, and GIS data to pinpoint leaks, saving a million liters a day.
- High repeatability: BMW reuses a single dip-tank validation workflow across new models and global plants.
Workflows that score high on both sides are where digital twins earn their keep, while workflows that score on neither are where digital twin programs go to become permanent pilots (more on these value areas below in our Insights+ Exclusive).
Further research
Below, in our Insights+ section, we share a few insights from the Digital Twin & Simulation Software Market Report 2026–2030, including vendor market shares in the narrow digital twin market, 3 drivers and 4 inhibitors for the digital twin market, and the highest-value areas for digital twins.
Click here to continue reading with Insights+
Access key market data for $99/month per user
The Insights+ Subscription unlocks exclusive facts & figures. You will gain access to:
- Additional analyses derived directly from our reports, databases, and trackers
- An extended version of each research article not available to the public
Full report access not included. For enterprise offerings, please contact sales: sales@iot-analytics.com
Share this with others:
[social_warfare]

Knud Lasse Lueth
Since founding IoT Analytics in 2014, my focus has been to build a team that produces high-quality research in areas such as IoT, AI, Cloud, and smart manufacturing. Throughout my journey, I have authored or co-authored over 100 reports, always with a commitment to delivering analyses that are not only trustworthy but also rich in insight and uniqueness.
LATEST NEWS


WHAT'S TRENDING
Data Science
5 Imaginative Data Science Projects That Can Make Your Portfolio Stand Out
OCT 05, 2022


Similar articles you can read

Federated AI Learns to Spot IoT Cyberattacks Without Sharing Private Data
SOURCE: BIOENGINEER.ORG
OCT 04, 2026

How smart home tech is shaking up home insurance — why smart sensors, AI, and IoT devices are revolutionizing how we protect our homes
SOURCE: TECHRADAR.COM
SEP 27, 2026

Deutsche Telekom Ties Iridium Satellites Into IoT Roaming as Bernstein Trims Its Rating
SOURCE: AD-HOC-NEWS.DE
SEP 27, 2026


Iridium, Deutsche Telekom and Toyota Test NB-IoT Voice Messaging Over LEO Satellites
SOURCE: IOTBUSINESSNEWS.COM
SEP 10, 2026